Responsible Borrowing: How to Spread Out Major Expenses Over Time

Responsible Borrowing: How to Spread Out Major Expenses Over Time
Big expenses can catch anyone off guard—whether it’s buying a new car, renovating your home, or covering a major life event. Borrowing can be a practical way to manage these costs, but it’s important to do it wisely. With careful planning, you can spread out expenses over time without losing control of your finances. Here’s a guide to borrowing responsibly and keeping your financial health on track.
When Does Borrowing Make Sense?
Taking out a loan can be a smart move when it’s used for investments or necessary expenses that add long-term value. Examples include:
- Home improvements that increase your property’s value.
- Education or training that can boost your future earning potential.
- Reliable transportation that’s essential for work or family needs.
On the other hand, borrowing for short-term pleasures—like vacations or luxury items—should be considered carefully. Ask yourself whether the purchase will still feel worthwhile once the loan is fully repaid.
Know Your Finances and Your Limits
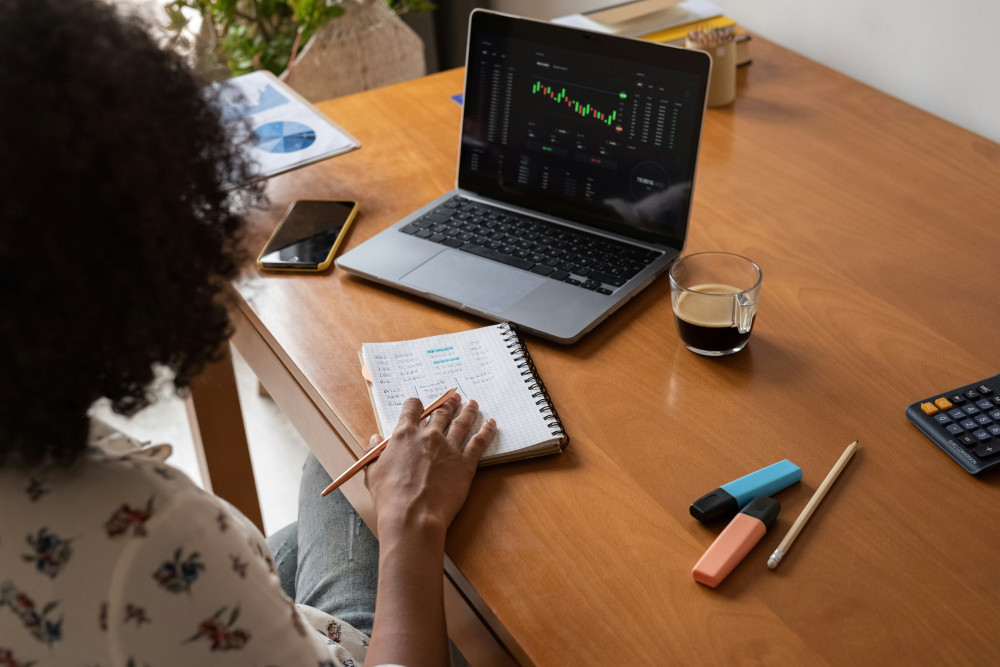
Before borrowing, take a close look at your financial situation. Create a realistic budget that includes all your fixed expenses, variable costs, and savings goals. This will help you determine how much you can comfortably afford to pay each month.
A good rule of thumb is that your total debt payments—including mortgage, car loans, and credit cards—shouldn’t exceed about 30–40% of your take-home pay. Staying within this range gives you room for unexpected expenses and helps prevent financial stress.
Compare Loan Options and Understand the True Cost
Not all loans are created equal. Interest rates, fees, and repayment terms can vary widely between lenders. When comparing options, pay attention to:
- APR (Annual Percentage Rate) – the most accurate measure of a loan’s total cost.
- Loan term – a longer term means smaller monthly payments but higher overall interest.
- Flexibility – check whether you can pay off the loan early without penalties.
Use online loan calculators to estimate payments, but always read the fine print before signing any agreement.
Læs også:
Consider Alternatives to Borrowing
A loan isn’t always the best solution. If the expense isn’t urgent, saving up over time can give you more freedom and peace of mind—without interest charges or long-term commitments.
Other options might include:
- Payment plans offered by retailers or contractors.
- Using existing savings or home equity instead of taking on new debt.
- Interest-free financing for certain purchases, if available.
The key is to choose the option that best fits your financial situation and comfort level.
Plan for the Future
When you borrow, you’re committing a portion of your future income. That’s why it’s important to think long-term. Consider how your finances would hold up if you lost your job, faced medical bills, or experienced other life changes. Building an emergency fund that covers three to six months of expenses can provide valuable security.
You might also explore insurance options that protect your income or loan payments in case of illness or unemployment.
Make Borrowing Part of Your Plan—Not a Burden
Responsible borrowing isn’t just about getting the money you need today—it’s about using credit as a tool to build stability and opportunity. When you understand your budget, compare your options, and borrow thoughtfully, a loan can support your goals rather than hold you back.
The most important thing is to stay in control and make decisions that align with your life and priorities. A loan should bring you peace of mind, not financial worry.
Læs også: